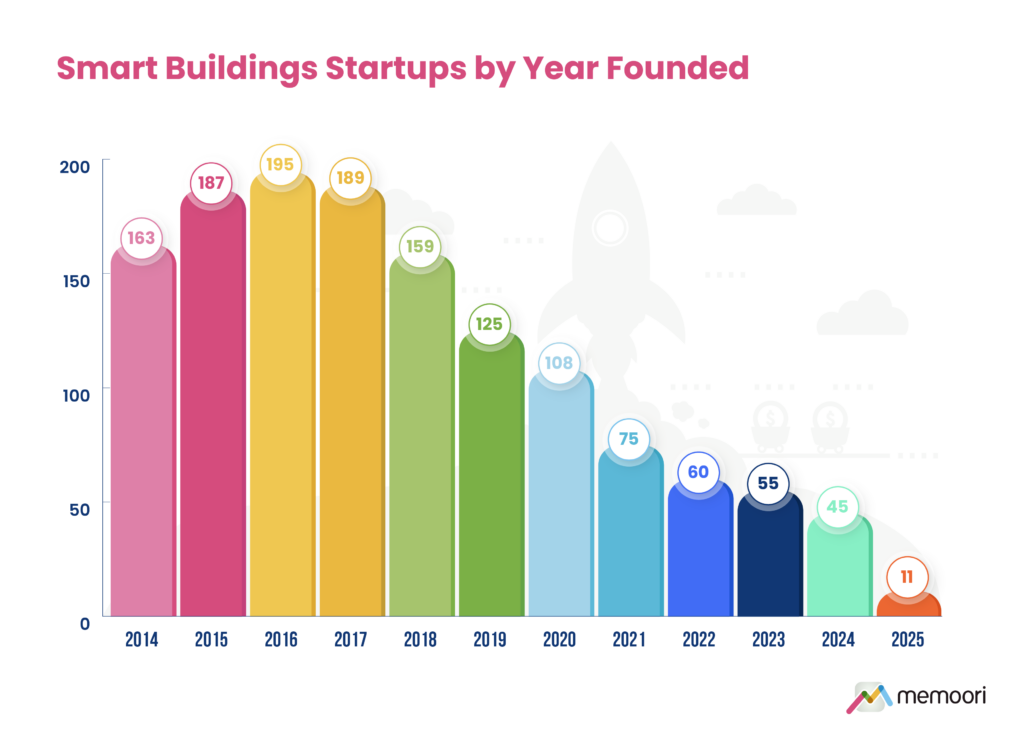
The smart building startup ecosystem stands at an inflection point. We’ve identified only 11 new smart building startups founded in 2025, and there has been a steady decline from the peak of 195 in 2016.
At the same time, acquisition activity has exploded, with 98 startup acquisitions in 2025, a 75% increase on 2024 and the highest annual total in the last decade!
In this live stream, we unpacked the data behind this transformation and what it means for investors, technology vendors, and building owners and operators. For the full analysis, take a look at our new report StartUps in Smart Buildings 2026.

Ecosystem Snapshot
For the purposes of our research, a startup is defined as a private company founded no earlier than 2014 (ten years old or younger) that focuses on the operation and maintenance phase of the commercial building lifecycle.
Our research has identified 1,372 startups founded since 2014 within this sector. Of these, 554 companies (approximately 40%) have been acquired over the past decade. Only 72 firms, representing 5% of the total, are classified as closed or inactive, though it’s important to note that many acquisitions likely represented companies heading toward closure or conducting fire sales rather than successful exits.
Currently, 51% of tracked companies remain active, though “active” encompasses everything from rapidly growing firms to those simply treading water.
Investment Trends
The investment landscape for smart building startups is changing dramatically. In 2025, we saw $6.5 billion invested across 281 rounds, a slight decrease from the previous year.
But here’s the interesting part: investors are writing bigger checks to fewer companies, favoring those with solid fundamentals over speculative bets. Evidence supporting this claim? The top 10 investments in 2025 accounted for $2.96 billion of the total $6.5 billion. So just under 46% of ALL capital invested last year.
Geographically, Europe has overtaken the Americas in the number of startups. Many of these European startups are focusing on decarbonization technologies like energy efficiency, HVAC optimization, sustainability, and grid-interactive buildings. Fifth Wall, a prominent US PropTech VC, recently cut staff and stopped active fundraising, citing high interest rates and the Trump Administration’s climate policies as factors in the decision.
The Innovation Pipeline: A Concerning Trend
Perhaps the most striking finding concerns new startup formation. In 2016, we tracked 195 new entrants to this market. In 2025, that number has fallen to just 11. While this figure may increase as we identify additional companies, the trend is unmistakable: the flow of innovation into smart building technology is being throttled.
Several factors contribute to this decline. Compared to sectors like artificial intelligence and robotics, smart building technology offers founders less favorable returns. Valuations in AI and robotics significantly exceed those in property technology.
The industry also presents structural challenges: operational technology markets move slowly, switching costs for commercial property buyers are high (whether real or perceived), sales cycles are lengthy, and incumbents hold strong positions. These conditions create a difficult environment for younger companies trying to gain traction.
Acquisition Activity
While investment has moderated and smart building startup formation has plummeted, acquisition activity tells a different story. We recorded 98 startup acquisitions in 2025, a 75% increase over 2024 and the highest annual total in the past decade, surpassing previous peaks in 2021 and 2022. Since 2014, we’ve tracked 554 total acquisitions.
This surge reflects growing recognition that success in this space requires more than technology alone. Implementation capabilities, partnerships, and industry connections are equally crucial, and acquisitions provide an efficient path to obtaining these assets.
Strategic Players: Driving Smart Building Consolidation
Strategic investors played a significant role in 2025, participating in approximately 23% of all investment rounds. These strategic relationships often serve as precursors to acquisition, progressing from minority stakes through co-development partnerships to full acquisition and platform consolidation.
Trane Technologies exemplifies this trend: the company committed approximately $720 million to M&A investments in 2025 and has announced plans to deploy between $2 billion and $2.5 billion in M&A activity this year.
AI and Digital Twins: Reshaping the Building Lifecycle
A report from Bluebeam indicates that only 27% of architectural, engineering, and construction firms currently use AI, but 94% plan to increase their AI investment this year. Strategic buyers are paying close attention, actively repositioning their portfolios around AI capabilities.
Our research profiles 84 startups applying digital twin and AI technologies across the building lifecycle, including 52 focused on AI applications and 32 on digital twin technology.
The concept of a “golden thread” of information running through a building’s entire lifecycle, from design and construction through operations, may finally be approaching reality, with AI serving as the catalyst to drive adoption forward.