The independent smart building AI specialist vendor is becoming an endangered species. Our new research tracked approximately $22 billion of disclosed mergers and acquisitions value across roughly 35 transactions in the 27 months to April 2026.
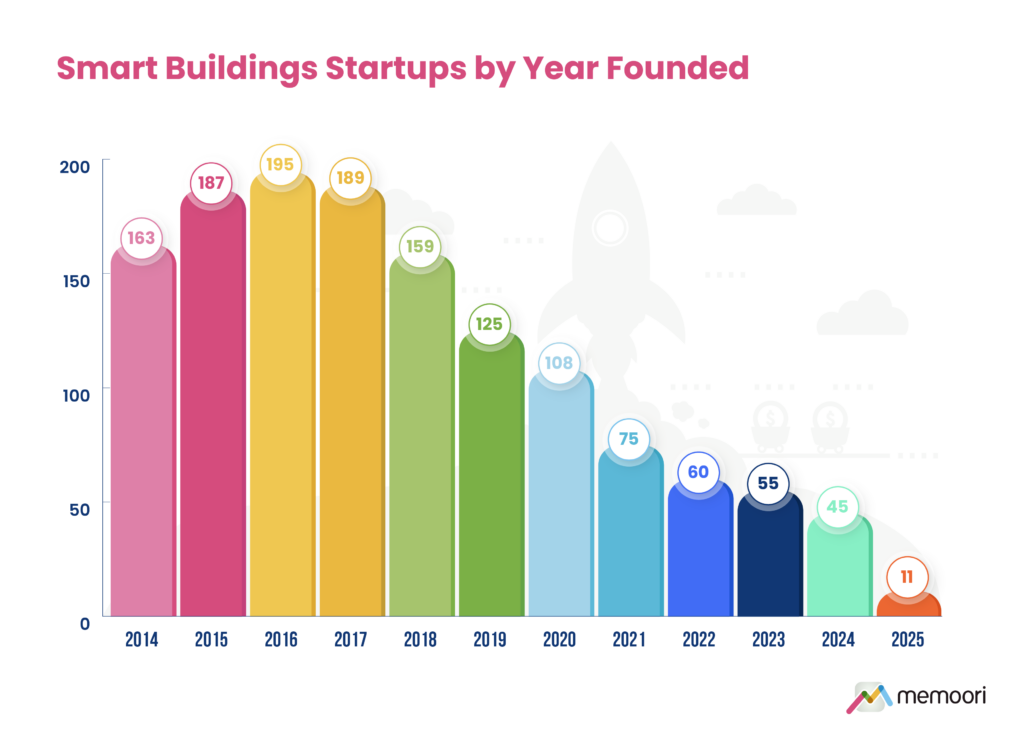
On the other side of the ledger, only 34 new companies entered the market across all 12 use case domains since 2022. Our startup ecosystem research found that just 11 new smart building startups were founded in 2025, the lowest annual total since the 2016 peak, while 98 startups were acquired in the same year, the highest annual total in the last decade.
The math is clear. AI-native specialists are being acquired far faster than new ones are forming. This is the defining structural shift in the smart building AI market heading into the second half of the decade.
From Build to Buy
The deals that reveal the most about the market’s direction are not the headline-grabbing multi-billion-dollar transactions. They are the capability acquisitions where established manufacturers purchased AI-native specialists to close gaps they could not fill internally.
Trane Technologies acquired BrainBox AI in January 2025, converting a two-year commercial partnership that had already produced the Trane Autonomous Control product into full ownership. Copeland announced its acquisition of Bueno in January 2026 to embed AI-enabled analytics into its refrigeration and HVAC portfolio. Mitsubishi Electric completed its approximately $1 billion purchase of OT cybersecurity specialist Nozomi Networks in January 2026, having first appeared as a Series E investor.
In each case, they chose to buy rather than build. Our report identifies this shift from “build internally” to “acquire capability” as the dominant incumbent strategy across energy optimization, HVAC controls, cybersecurity, and access control.
A Shrinking Pool of Smart Building AI Targets
The supply side is tightening in parallel. Across 454 companies tracked in the report’s dataset, 286 have recorded disclosed funding totaling $28.73 billion, but the distribution is heavily skewed.
A small number of large raises account for the bulk of that capital, while the typical funded company sits in the mid-single-digit to low-tens-of-millions range, enough to build a product, not enough to sustain independence against a determined acquirer.
The smart building AI vendor pipeline is not refilling. The 34 new entrants since 2022 are spread thinly, with Portfolio Analytics leading at eight companies and several domains recording one or zero. Companies formed between 2015 and 2019 still make up the largest cohort. The formation phase is contracting even as the total addressable market grows.
Strategic corporate investors are increasingly visible on startup cap tables, and our research identifies this as the most structurally significant investment pattern in the research window. Johnson Controls and Prologis Ventures co-led PassiveLogic’s Series C. Carrier participated in 75F’s Series B with white-labeling rights attached. These minority positions in smart building AI companies frequently precede full acquisition, narrowing the pool of independent targets further.
What This Means for Procurement
For building owners, operators, and facilities managers, the consolidation wave creates a concrete procurement problem: the vendor you select in 2026 may operate under different ownership by 2028. Our report projects consolidation will persist over the next few years, driven by EU Energy Performance of Buildings Directive timelines and US state-level Building Performance Standards.
The absorption of specialists into larger platforms reduces integration friction and brings advanced capabilities into systems buyers already use. But evaluation criteria should now extend beyond product performance to include ownership stability, the acquirer archetype most likely to absorb the vendor, and contract provisions that protect continuity through a change of control.
The window for selecting an independent smart building AI specialist is measurably narrowing. Procurement teams that recognize this structural shift, and the data behind it, will navigate the next five years more effectively than those that don’t.
Our full smart building AI analysis, including the 454-company dataset, M&A deal activity, funding distributions, and consolidation outlook, is available now.